

YNAB
ynab.com
- 4.5
- 4.59K Reviews
- 1.00M
- Downloads
- Free
- Price
Screenshots
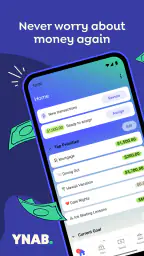
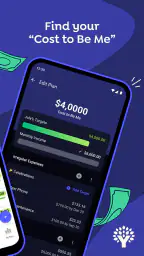
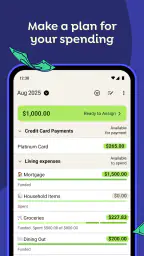
YNAB Pros and Cons
Pros
- User-friendly interface simplifies budgeting.
- Real-time sync across multiple devices.
- Customizable categories for personalized budgets.
- Comprehensive tutorials for beginners.
- Strong security measures protect user data.
Cons
- Subscription fee might deter some users.
- Limited features in the free trial version.
- Learning curve for non-budgeters.
- Requires internet for full functionality.
- No investment tracking features.
 Analysis by All-app
I judge a budgeting app by what it helps me decide before I spend, not just by how neatly it charts yesterday’s transactions. YNAB is built around that forward-looking habit: I assign the money I have to specific purposes, then use the plan to make trade-offs as life changes. That makes it a different kind of finance app from one that mainly tracks balances or sorts purchases into categories. It can be a good fit if you want to be hands-on with your budget; it is less appealing if you simply want a passive snapshot of your accounts.
Choose a budgeting style you will actually use
The first question I’d ask is whether you want to plan actively. YNAB asks you to look at available money and decide what it needs to cover, rather than relying on a projected monthly allowance that may not match the timing of your bills. If your income arrives in uneven chunks, or several priorities compete for the same dollars, that method can make the choices clearer. If your finances are already simple and you rarely need to adjust your spending, the extra attention may feel like work rather than help.
There is also a practical question about how much detail you enjoy. Some people like naming categories, checking them during the week, and moving money when plans change. Others would rather review a bank balance and leave the rest alone. I found it useful to start with only the categories that shape real decisions—housing, food, bills, upcoming costs, and a little flexible spending—rather than trying to build a perfect map of every purchase on day one.
A realistic example: imagine payday arrives while a car repair, groceries, and a planned weekend are all competing for attention. A balance-only view can make the total look comfortable without showing what is already spoken for. In YNAB, I would give money to the repair first, cover the essentials, and then see what remains for the weekend. The value is not that the app makes the decision for me; it makes the trade-off visible before I spend.
Why its hands-on method can pay off
The strongest reason to choose this approach is that it brings planning and spending into the same routine. Rather than treating a budget as a monthly document I create once and forget, I can revisit the categories when a bill changes or an unexpected expense appears. That small act of reallocating money is useful in its own right: it makes me acknowledge what I am choosing to delay instead of quietly hoping everything will fit.
One less obvious habit that helps is to treat irregular costs as regular planning problems. Annual renewals, seasonal expenses, and replacement purchases may not arrive every month, but they are not surprises if I know they are likely. I can create a place for them in the budget and add money over time. This is more helpful than letting a large occasional bill land in the same category as everyday spending, where it can make an otherwise reasonable month look confusing.
I also find it helpful to check a category before making a discretionary purchase, not after. That turns the budget into a live answer to “can I afford this now?” rather than a report card on what I already did. If the category is short, I can decide whether to move money from another priority or wait. That is a small workflow change, but it is where a planned budget becomes more practical than a list of past transactions.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What YNAB feels like in daily use
The app comes from ynab.com and sits in the finance category. It is free to download, rated for Everyone, and has an average rating of 4.5 from around 24,000 ratings, with roughly 4,600 written reviews and over a million installs. Its current version is 26.5.1, and the app’s release history begins in 2015. Those figures suggest a well-established product, though popularity alone cannot tell you whether its budgeting routine suits you.
Where other money tools may fit better
Compared with a basic expense tracker, YNAB asks for more input but gives me a more active role in deciding what comes next. A tracker is often the easier choice if my main goal is to see where money went, with as little maintenance as possible. A spreadsheet can be better for someone who wants complete control over layout and calculations and does not mind maintaining it. A bank’s built-in tools may be convenient when I only need a quick overview in the same place I check balances. Those alternatives are not lesser by default; they simply put less emphasis on assigning each available dollar a job.
YNAB is most compelling when the problem is not a lack of transaction history but a lack of clarity about priorities. It may be too involved for someone who does not want to review a plan regularly, or for a person who expects an app to make financial decisions automatically. It also cannot make a tight budget comfortable by itself. If essential costs already exceed income, the app can help show the gap and organize choices, but the hard decisions still belong to the user.
Account linking is one possible way to bring transactions into a budget, but I would not make linking the only way I can keep the plan current. If I prefer not to connect accounts, or if a transaction has not appeared yet, entering and checking activity manually can keep the budget aligned with reality. Either way, I would verify important purchases and balances rather than assume that a screen is automatically up to date. The key is to choose a routine I can maintain, not the most automated setup available.
Switching takes more than installing an app
Moving from another budget usually means rebuilding the categories and deciding what to do with money already set aside. I would make the change at a natural checkpoint, such as the start of a new pay period, and bring over only the categories I understand and actively use. That is less frustrating than copying years of labels that no longer guide current decisions. I would also keep the old method accessible briefly, so I can check an upcoming bill or reconcile a confusing transaction while learning the new workflow.
The app is free to download, but in-app purchases range from $14.99 to $109.00 per item. I would weigh that ongoing commitment against how often I expect to use the planning process, rather than assuming the download price tells the whole story. Someone who checks a budget only once in a while may be better served by a simple spreadsheet or a free tool they already use. For me, paying makes more sense when regular planning prevents avoidable overspending or helps me prepare for costs that otherwise arrive as a shock.
To make the first stretch easier, I would avoid trying to account for every small detail immediately. Start with the next bills and the priorities that could genuinely compete for money; then refine categories as questions come up. When spending changes, move money deliberately instead of treating the original plan as a rule that cannot bend. That flexibility is important: the aim is to make a realistic plan and adjust it, not to feel that one unexpected purchase has ruined the whole month.
My recommendation
YNAB is a strong choice for people who want a budget to guide decisions, especially if their income or expenses require active prioritizing. It can also suit someone who is trying to build a buffer gradually, because the plan gives upcoming needs a visible place rather than leaving them buried in a general balance. I would skip it if I mainly want automatic summaries, dislike checking categories, or have no interest in changing spending habits. In those cases, a lighter tracker or a familiar spreadsheet may be easier to stick with.
For me, the deciding factor is whether I am willing to spend a little time with my money before spending it. If I am, the method offers a useful structure without pretending that budgeting removes every financial constraint. If I want a tool that stays out of the way, it is probably not the right match. That is a more honest test than choosing based on ratings or a polished interface.
Diving into YNAB is like having a budgeting coach right in your pocket. The onboarding process is super friendly, offering a step-by-step guide that even my tech-challenged aunt could follow. You start by linking your bank accounts, which, I admit, felt a bit nerve-wracking at first. But YNAB’s encryption standards are top-notch, so you can breathe easy knowing your data is safe.
Once you’re all set up, YNAB encourages you to "give every dollar a job." This philosophy seems simple, but it’s incredibly effective. It forces you to think about your priorities and make intentional decisions about your spending. I quickly realized how much I was spending on things I didn’t really need, like that third streaming service I barely use. Oops!
Features That Stand Out
What truly sets YNAB apart are its features designed to change your financial mindset. The app uses a zero-based budgeting approach, which might sound complex, but it’s actually quite liberating. You allocate every dollar to a specific purpose, whether it’s rent, groceries, or savings for that dream vacation. No more money just floating around without a plan!
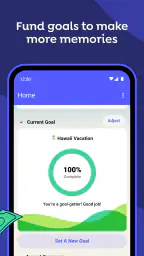
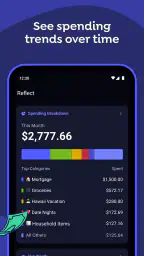
YNAB also offers some cool tools to keep you on track. The goal tracking feature is fantastic for setting long-term financial targets. I’ve set a goal to save for a new laptop, and seeing my progress inch closer each month is incredibly satisfying. Plus, the reports section breaks down your spending patterns, helping you spot trends and make adjustments.
Another handy feature is the age of money metric. It tells you how long your money sticks around before it’s spent. The idea is to increase this number, giving you a buffer and reducing financial stress. It’s like a personal challenge, and I’ve found myself getting competitive with my past self!
Ease of Use and Accessibility
YNAB is available on both Android and iOS, and it syncs seamlessly across devices. I’ve used it on my phone, tablet, and laptop without a hitch. The interface is clean and intuitive, which means you spend less time figuring out what to do and more time actually doing it. The app’s design is minimalistic, focusing on functionality rather than flashy aesthetics.
The support community is a hidden gem. Whether you’re a newbie or a seasoned budgeter, you’ll find a wealth of knowledge in the forums and video tutorials. I’ve learned a lot from fellow users who share their tips and experiences. It’s like having a supportive financial family cheering you on!
Challenges You Might Face
It’s not all sunshine and rainbows, though. YNAB does come with a learning curve, especially if you’re not used to thinking about money in this structured way. Initially, it felt like a chore to update my budget regularly. But once you get the hang of it, it becomes second nature.
Also, YNAB is a paid service, which might be a deal-breaker for some. There’s a free trial, but after that, you’ll need to subscribe. However, I view it as an investment in my financial health. The savings and peace of mind it has brought me far outweigh the cost.
Final Thoughts
All in all, YNAB is more than just a budgeting app; it’s a lifestyle change. It’s about taking control of your finances and being proactive rather than reactive. If you’re tired of living paycheck to paycheck or just want to have a better grasp on your financial future, I’d say give YNAB a shot. It’s helped me sleep better at night knowing exactly where my money is going and how I’m progressing toward my goals. So, why not take the plunge and see how it can transform your financial life?
Frequently Asked Questions
What is YNAB and how does it work?
YNAB, short for 'You Need A Budget,' is a personal finance app designed to help users manage their money more effectively. It operates on a zero-based budgeting system, meaning every dollar is assigned a specific purpose. The app encourages proactive financial planning by allowing users to categorize expenses, set financial goals, and monitor spending habits.
Is YNAB suitable for beginners in budgeting?
Yes, YNAB is highly suitable for beginners. It offers a user-friendly interface with tutorials and guides to help new users understand budgeting principles. The app simplifies complex financial concepts and provides resources like workshops and support forums to ensure users can effectively manage their finances, regardless of their experience level.
Can YNAB connect to my bank accounts?
YNAB offers the ability to connect directly to your bank accounts, allowing for automatic transaction import. This feature helps keep your budgeting up-to-date without manual entry. However, users can also enter transactions manually if preferred, providing flexibility in how they choose to manage their financial data.
What platforms is YNAB available on?
YNAB is available on multiple platforms, including Android, iOS, Windows, and macOS. It also offers a web-based version, ensuring users can access their budget from virtually any device. This cross-platform availability allows for seamless synchronization and access to financial data on-the-go.
Does YNAB offer a free trial?
YNAB provides a free 34-day trial for new users, allowing them to explore all features without commitment. This trial period is beneficial for those who want to experience the app’s functionality and determine if it meets their budgeting needs before subscribing to the paid version.


